HomeReverse mortgage 101
Reverse mortgage 101 · A homeowner’s guide
Not a scam. Not a last resort. A loan, explained.
How these loans work, what you might qualify for, when they tend to make the most sense — and the protections built into every loan.
Draft: video not made yet
3
Ways to access your equity
HECM, proprietary, second
4
Myths, busted
The ones that stop people calling
5
Steps, start to finish
From first question to funding
5
Protections in every loan
Built in, not bolted on
You keep the title to your home — the lender does not own it.
What is a reverse mortgage?
Your equity, turned toward you.
If you're 62 or older (55+ for some programs) and own your home, a reverse mortgage lets you convert part of your home's equity into cash — without taking on a new monthly mortgage payment. This guide walks through the basics, what you might qualify for, three situations where a reverse mortgage is often the right tool, and the safeguards that make today's loans very different from what you may have heard about years ago.
Property taxes, homeowners insurance, HOA dues and upkeep remain yours.
Draft: compliance line, Todd’s OK owed
A reverse mortgage is a loan secured by your home — similar in concept to a home equity line of credit (HELOC), except monthly repayment is optional. Instead of writing a check to your lender every month, interest and fees are added to the loan balance over time. The full balance isn't due until you sell the home, permanently move out, or pass away.
Reverse mortgages are not a scam, and they're not just a “loan of last resort.” They're a federally regulated financial tool that a growing number of retirees use proactively, as one piece of a broader retirement plan — not only in an emergency.
The basics
Five facts that change the conversation.
1
You keep the title to your home — the lender does not own it.
2
No monthly mortgage payment is required (you're always free to pay more, or pay it down, if you choose).
3
You remain responsible for property taxes, homeowner's insurance, and maintaining the home.
4
The loan is non-recourse: you or your heirs will never owe more than the home is worth when it's sold.
5
You must live in the home as your primary residence to keep the loan in good standing.
Three ways to access your equity
One category. Three doors.
“Reverse mortgage” isn't a single product — it's a category. Here are the three most common paths, and who each one tends to fit.
Min. age
62+
HECM
The FHA-insured reverse mortgage — federally regulated and non-recourse. The most common program, available once the youngest borrower turns 62.
Min. age
55+
Proprietary
A conventional-equivalent (“jumbo”) reverse mortgage for higher-value homes outside FHA limits, available to borrowers as young as 55.
Min. age
55+
Reverse Mortgage Second
A second lien behind your existing first mortgage — keep your low-rate first in place while accessing more equity, available to borrowers as young as 55.
How much could you borrow?
Age sets the ceiling. Rates set the room.
How much you can access comes down to two things: the age of the youngest borrower on title, and current interest rates. Generally, the older you are, the more of your home's value you can access — because the loan is projected to be outstanding for fewer years.
Maximum percentage of your home's value available to borrow, by age of the youngest borrower and program:
Age
HECM
Proprietary
Reverse Second
62
35%
41%
65%
72
41%
48%
65%
80
48%
55%
65%
Illustrative example based on rates and program guidelines as of August 2026; not a loan offer, commitment, or approval. Actual available loan amount depends on the borrower's age, current interest rates, home value, existing liens, and underwriting at the time of application, and will vary by lender and investor guidelines. Reverse mortgages are loans and must be repaid; borrowers must maintain the home, pay property taxes, and keep homeowner's insurance current.
Draft: Aug 2026 table; book draft has a Sept table, Todd to choose
Your home, your numbers
Curious what this looks like for your home? Send your age, estimated home value, and zip code, and I'll run the exact numbers for you — no obligation.
Todd Walcott
Used deliberately, it's a planning tool.
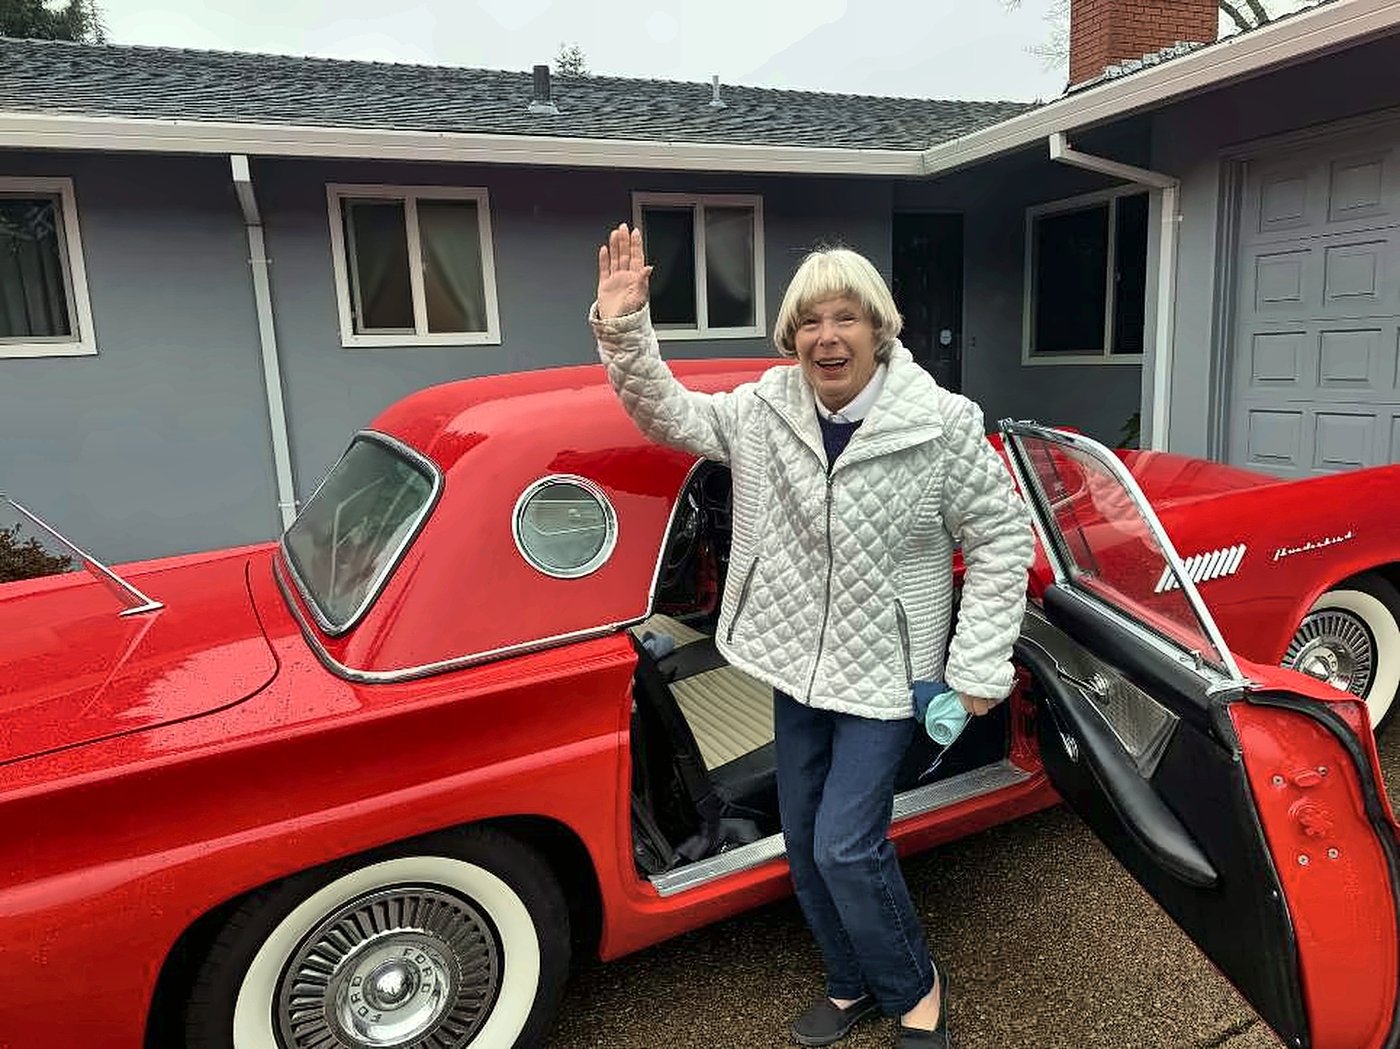
Todd and his mom
Where it can be the right tool
Three strategies hiding in plain sight.
A reverse mortgage isn't only for homeowners facing a cash shortfall. Used deliberately, it's a planning tool. Three of the most common — and most underused — strategies:
Planning with an advisor?
Call or text Todd
(760) 808-4500
1
Buying More Home Than Cash Alone Would Allow
Many people assume the only way to buy retirement housing without a monthly mortgage payment is to pay all cash. A HECM for Purchase lets you buy your next home using a combination of home-sale proceeds (or other funds) and reverse mortgage proceeds in a single transaction — often preserving tens or hundreds of thousands of dollars that would otherwise be tied up in the new house. You still end up with no required monthly mortgage payment, but you've kept more cash available for investments, emergencies, or simply peace of mind.
2
Retiring Existing Forward Mortgage Debt
If you're carrying a traditional mortgage payment into retirement, a reverse mortgage can pay off that balance and eliminate the monthly obligation entirely — freeing up cash flow right when income sources shift from a paycheck to savings, Social Security, and pensions. This is one of the most common and most straightforward uses of the product.
Property taxes, homeowners insurance, HOA dues and upkeep remain yours.
Draft: compliance line, Todd’s OK owed
3
A Buffer Asset for Down Markets — Managing Sequence-of-Withdrawal Risk
One of the most overlooked uses of a reverse mortgage is as a strategic reserve alongside an investment portfolio. “Sequence of withdrawal risk” (also called sequence-of-returns risk) is the danger that a market downturn early in retirement, combined with ongoing withdrawals, can permanently damage a portfolio's ability to recover — even if average returns over the long run look fine.
A HECM line of credit can act as a buffer asset: in years when the market is down, a retiree can draw from the reverse mortgage line instead of selling depreciated investments to cover living expenses, giving the portfolio time to recover before those assets are touched again. A notable feature of the HECM line of credit is that the unused portion grows over time regardless of home value — so a line opened early and used sparingly can become a meaningfully larger resource years later. This is increasingly used by fee-only financial planners as a coordinated part of a retirement income and withdrawal strategy, not as a stand-alone product.
This is general education, not personalized investment or tax advice. Every household's situation is different — this strategy is best evaluated together with your financial advisor.
Common myths, busted
What you heard, and what’s true.
Myth
“This is a loan of last resort.”
Fact
Borrowers increasingly use reverse mortgages proactively as part of a retirement plan — not only in an emergency.
Myth
“My kids will get stuck with a huge bill.”
Fact
Reverse mortgages are non-recourse loans. If the balance is ever higher than the home’s value, heirs are never responsible for the difference.
Myth
“I can’t leave my house to my kids.”
Fact
Heirs can keep the home by repaying the balance (often through a refinance or sale), and many borrowers choose to draw less equity early to preserve more for heirs later.
Myth
“There are a lot of hidden fees.”
Fact
With the exception of required HUD counseling and, for HECM loans, FHA insurance, costs are generally the same as a traditional forward mortgage.
Draft: cost sentence flagged for Contempo compliance review
The process: what to expect
Five steps. No surprises.
Step 1
Education
A licensed loan officer reviews your goals and financial situation to help determine if a reverse mortgage fits — this is the time to get every question answered.
Step 2
Counseling
Independent counseling with a HUD-approved counselor (no affiliation to lenders) is required, usually 60–90 minutes, in person or by phone.
Step 3
Application
Your loan officer walks you through exactly which documents are needed and handles the paperwork with you.
Step 4
Processing & Appraisal
Your application is submitted for processing and a home appraisal is scheduled to confirm value and livable condition.
Step 5
Closing
Once approved, you sign final documents. Any existing mortgage is paid off from the proceeds, a rescission period applies, and then the loan funds.
Or call or text
(760) 808-4500
Built-in consumer protections
Guardrails, written into the loan.
1
Non-recourse loan: you or your heirs never owe more than the home's value when it's sold.
2
Independent, HUD-approved counseling is required before you can apply, with no affiliation to lenders.
3
FHA insurance backs every HECM loan.
4
Non-borrowing spouse protections allow an eligible spouse to remain in the home after the borrower passes away.
5
Second-appraisal safeguards help protect against an inaccurate home valuation.
Todd and his mom
Is a reverse mortgage right for you?
Five questions worth asking first.
A reverse mortgage is a great solution for many, though not all. Ask yourself:
1
What are my retirement goals, and how close am I to reaching them?
2
Is my current home still meeting my needs?
3
Would an unexpected expense take my retirement plan off track?
4
Do I want to leave my home to my heirs — and do they actually want that?
5
Where do I want to be in five years, and what's holding me back from getting there?
Every homeowner's situation is different — the only way to know your real numbers is to run them.
Run your own numbers
One page. Your figures, in ink.
Here’s a worksheet you can use to help you and your originator determine if a reverse mortgage is right for you:
Your Reverse Mortgage Worksheet
Draft: PDF not on file, link to come
Back matter
Worksheet: Your Own Numbers
Every dollar figure in this book belongs to someone else's situation. Use this page to write down your own — either before your first call, or during it, so you walk away with something in writing.
My age (and my spouse's age, if applicable)
Estimated home value
Current mortgage balance
Current monthly mortgage payment
Other monthly debts (cards, auto, etc.)
What I'd want the funds for (payment relief, credit line, purchase, other)
Estimated available loan amount (ask your loan officer to fill this in)
Questions I still have before deciding
Bring this page to your first call with a loan officer — 760.808.4500 — or email a photo of it to todd@contempolending.com and I'll run the numbers before we even speak.
106
A preview of the worksheet
Draft: builder places the worksheet image from Todd’s document
Read first. Call when you’re ready.
The whole book is free, the estimate needs no name, and the phone is answered by Todd.
Draft: video not made yet